<img src="https://events.xg4ken.com/pixel/v2?tid=KT-N2BAB-3ED&amp;noscript=1" width="1" height="1" style="display:none">
Skip to the main content.

6 min read

How Much of Your Credit Card Should You Use? (30% Rule)

How Much of Your Credit Card Should You Use?

How much of your credit card should you use? Aim to keep your balance below 30% of your credit limit, and under 10% if you want the best possible credit score. On a card with a $1,000 limit, that means keeping your balance under $300, or under $100 for top-tier results. Paying your card in full each month is even better, since carrying a balance doesn’t help your score.

Managing a credit card can feel like walking a tightrope, with everyday convenience on one side and your credit score on the other. Below, we’ll break down how credit utilization works, show you how much to spend on common credit limits, and share simple ways to keep your usage in check.

What Is a Credit Utilization Ratio?

Your credit utilization ratio is a simple calculation of how much credit you’re using compared to how much is available to you. This ratio is one of the key factors lenders look at when assessing your creditworthiness. It's also one of the main components that impact your credit score, making up about 30% of your total score. The lower your credit utilization ratio, the better.

How Much of Your Credit Card Should You Use - a person happy about their credit card

For instance, let’s say you have a credit card with a limit of $1,000, and you regularly carry a balance of $500. This means you’re using 50% of your available credit, which can be considered high by lenders. Ideally, you want to aim for a utilization rate of 30% or lower to keep your credit score in good shape. Lower is even better. People with the highest credit scores tend to keep their utilization under 10%. Scoring models also look at both your overall utilization across all your cards and the utilization on each individual card, so it’s smart to keep every card in check, not just your total.

Now imagine your cousin Joe, who’s always pushing his credit cards to the max. He’s not in terrible shape credit-wise, but every month he’s using nearly 100% of his limit. Joe insists he’s “handling it” because he prefers to use cash for everything else. While Joe’s approach hasn’t destroyed his credit, it’s not doing him any favors either. If Joe talked to a First Alliance Credit Union Member Advisor, they might recommend strategies to bring his utilization ratio down, which would give him more financial breathing room and a better shot at future credit approvals.

How Much Should You Spend on Your Credit Card? (By Credit Limit)

If you’ve ever wondered, “If my credit limit is $500, how much should I spend?” the math is simple: multiply your limit by 0.30 to follow the 30% rule, or by 0.10 to hit the under-10% goal. Here’s what that looks like for common credit limits:

Credit Limit Stay Under (30%) Best for Your Score (10%)
$300 $90 $30
$500 $150 $50
$1,000 $300 $100
$1,500 $450 $150
$2,000 $600 $200
$5,000 $1,500 $500
$10,000 $3,000 $1,000

Keep in mind these numbers apply to the balance that shows up on your statement, not to how much you swipe during the month. You can spend more than 30% and still keep your utilization low by paying part of it off before your statement closes, since that’s usually when your card issuer reports your balance to the credit bureaus.

How to Keep Your Credit Utilization Below 30%

How Much of Your Credit Card Should You Use - social - a person showing their credit cards

Now that we understand what credit utilization is, let’s explore best practices for keeping it in a healthy range. The good news is that this is something you have direct control over, unlike factors like the age of your credit accounts.

1. Keep Your Balance Below 30%

The rule of thumb is to keep your credit card balance below 30% of your total available credit. If your credit limit is $2,000, you should aim to keep your balance below $600. This shows lenders that you’re responsible and not over-relying on credit.

2. Pay More Than the Minimum

If possible, try to pay off your balance in full every month. This not only keeps your utilization low but also helps you avoid paying unnecessary interest. If you can’t pay it off entirely, make sure you pay more than the minimum to bring down your balance faster.

3. Spread Out Purchases

If you have multiple credit cards, avoid maxing out one while leaving others untouched. Instead, spread your purchases across multiple cards to keep individual utilization rates low. This can also give your overall utilization a boost.

4. Increase Your Credit Limit

If you find it hard to stay below the 30% threshold, consider asking for a credit limit increase. Just be careful not to view the increase as an excuse to spend more!

What is credit utilization? Find out on this video!

So if your like Lisa, a recent college graduate, just got her first job and is trying to save for a car. She has a $1,500 credit card limit and usually spends around $600 a month. That puts her credit utilization at 40%, which could hurt her credit score over time. After speaking with a First Alliance Member Advisor, she decides to start paying off part of her balance twice a month and to apply for a small increase to her credit limit. Now, her utilization sits comfortably at around 20%, helping her save for the car and build good credit.

Start budgeting today! Get your free budgeting worksheet!

Monitoring and Managing Your Credit Usage Effectively

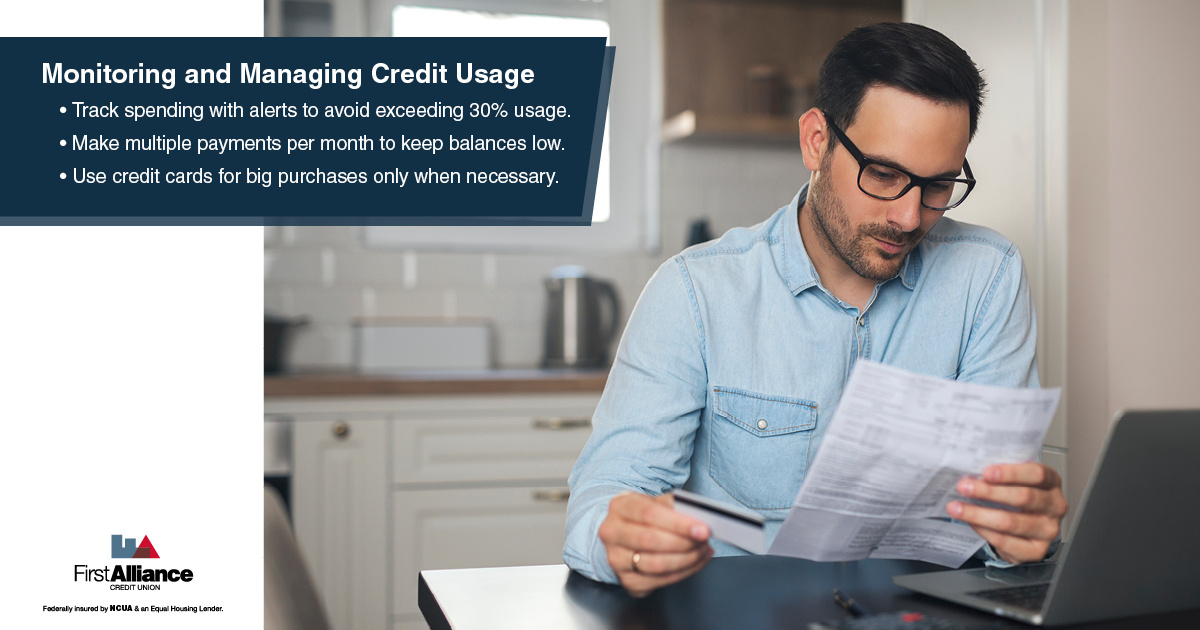
How Much of Your Credit Card Should You Use - a person monitoring their card usage

Managing credit utilization isn’t just about reducing how much you owe — it’s also about being aware of how and when you use your credit. Here are a few strategies to help you stay on top of your credit utilization and keep your credit score in check.

1. Track Your Spending Regularly

It’s easy to lose track of how much you’re charging to your credit card. Set up spending alerts to notify you when you’re approaching a certain percentage of your credit limit. This way, you can avoid inadvertently exceeding that 30% mark.

2. Make Multiple Payments in a Month

Rather than waiting for your due date, consider making payments throughout the month. This helps keep your reported balance low, which in turn keeps your utilization ratio low. Even if you only pay a small amount each week, it can make a big difference in your score.

3. Use Credit Cards for Big Purchases Only When Necessary

While it might be tempting to use your credit card for everything, especially to earn rewards, be mindful of how quickly balances can add up. It’s fine to use your card for big purchases, like appliances or furniture, but only if you have a plan to pay it off quickly.

Use your credit card and earn rewards!

Take Izumi, your neighbor who swears by her credit card for racking up airline miles. She recently put a new TV on her card but then remembered she was already close to 30% utilization. Instead of risking a ding to her credit score, she quickly set up two payments for the next two weeks to bring her balance back down before her credit report updated. Now she’s enjoying her new TV and keeping her credit in check.

Frequently Asked Questions

Talk to a First Alliance Credit Union Member Advisor

How Much of Your Credit Card Should You Use - a couple looking at their credit card

Now that you know how much of your credit card you should use, keeping your utilization in check is one of the easiest ways to manage and improve your credit score. Stop by a First Alliance branch in Rochester or reach out online, and a Member Advisor can help you build a plan that fits your budget.

If you’re like Joe, Lisa, or Izumi and want to discuss personalized strategies for improving your credit card usage, consider reaching out to a  First Alliance Credit Union Member Advisor. They can help you develop a plan to keep your utilization ratio low, increase your credit limits responsibly, and ultimately get more out of your financial life. Keeping track of your credit utilization isn’t just about improving your score—it’s about staying financially healthy and making sure you’re in control of your credit, rather than the other way around.

Have more questions about credit cards? Ask us!

Demystifying Credit Card Terminologies: A Guide for Young Adults

Demystifying Credit Card Terminologies: A Guide for Young Adults

Demystifying Credit Card Terminologies: Understand APR, credit limits, balance transfers, and more. Explore essential credit card terminologies!
Read More
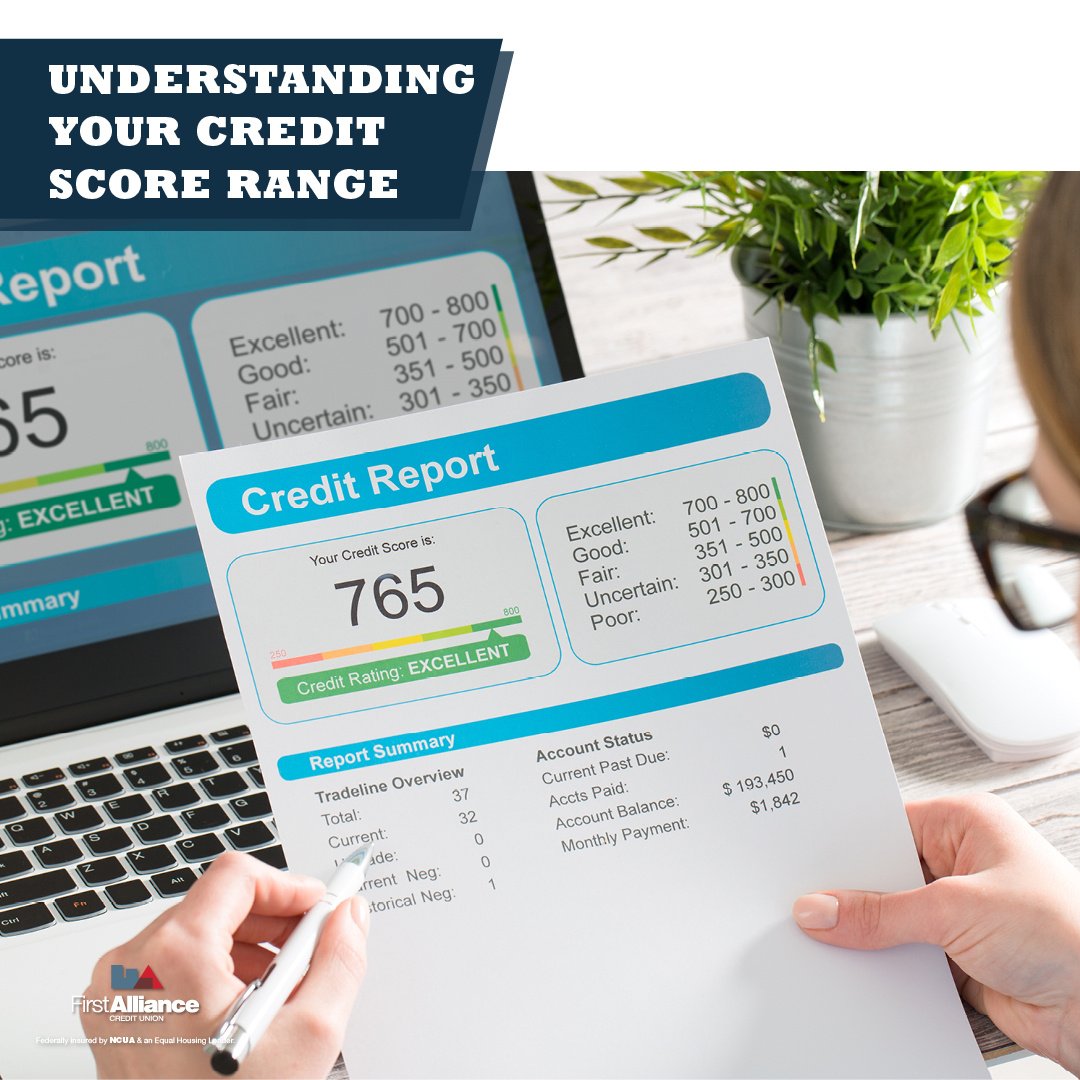
Understanding Your Credit Score Range

Understanding Your Credit Score Range

Understand Your Credit Score Range and learn how to understand & improve your credit score for better financial opportunities & peace of mind.

Read More
What Happens If You Don’t Use Your Credit Card?

What Happens If You Don’t Use Your Credit Card?

Learn how letting your credit card sit idle can impact your credit score and discover strategies to keep it active without accumulating debt.

Read More