 Jenna Taubel
Why Bother with a Savings Account?
 Chris Gottschalk : Aug 29, 2019, 4:40:00 AM
The most basic step you can take when starting to save money is opening a savings account. Sometimes, though, this can seem like an unnecessary...
A savings account is a place for you to store money that isn’t being used in a secure place where it can earn interest, which grows your overall savings. Savings accounts help you distinguish between everyday spending money and the cash that’s meant for a later date, so that you can avoid overspending, over drafting, and fees.
Savings accounts generally require you to keep a minimum balance and most financial institutions offer you an interest rate to help you grow your savings. The interest you earn on your account will be compounded daily or monthly. Interest rates can vary among financial institutions, so you'll want to search for the best savings account rates before opening an account with a financial institution.
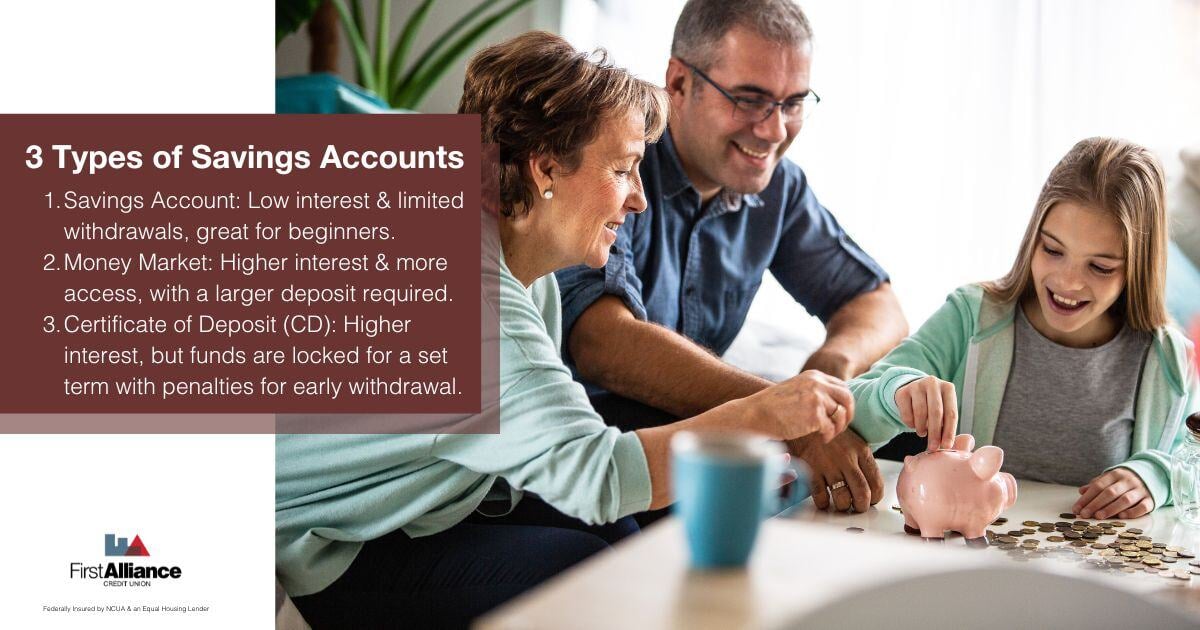
There are many different kinds of savings accounts. The three most common types of savings accounts include basic savings accounts, money market accounts, and certificates of deposit. Each savings account type earns interest, but typically have different minimum balance requirements and withdrawal limitations.
A basic savings account is a place to simply hold money you don't plan to spend. You can add funds to a basic savings account at any time. However there are limits on how often you can withdraw funds from a basic savings account in a month. These types of savings accounts typically have low interest rates and are best for those just getting started with saving money.
A money market account is similar to a savings account, but you typically have an easier time accessing your money. You can often write checks or use a debit card to withdraw funds out of a money market savings account. The interest rates are also typically higher with a money market account than a basic savings account. A money market account does come with limitations though; it has limits on how many times you can make withdrawals per month and also requires larger minimum deposit to open and maintain the account. A money market account is better suited for those looking to earn interest on a higher dollar amount but still maintain accessibility to funds. Many people use money markets accounts for emergency savings funds.
Lastly, certificates of deposit are also type of savings account. The key difference is that they lock your money into the account for a certain amount of time, usually anywhere from 6 months to 5 years. In return, you receive a higher interest rate than with a basic savings account, and generally, the longer the term, the higher the rate. You can withdraw the money early, but it usually comes with an early withdrawal penalty, so a CD works best for money you won't need right away.
Yes! Savings accounts are federally insured either by the Federal Deposit Insurance Corporation (FDIC) for banks, or the National Credit Union Administration (NCUA) for credit unions. What this does for you is if the financial institution goes out of business, you will not risk losing your money. The NCUA insures deposits at credit unions up to $250,000 per share owner, per insured credit union, for each account ownership category. The FDIC insures deposits at banks up to $250,000. You can learn more about how this insurance works in the video below.
To open a savings account of any kind you will need to provide a few pieces of personal information to start the process:
Besides your personal information, you'll also need an initial deposit to open your savings account. Each financial institution sets its own minimum deposit requirement, so it's worth comparing accounts before you open one. Some financial institutions also offer online account opening, while others require you to be there in-person to get started.

 Chris Gottschalk : Aug 29, 2019, 4:40:00 AM
The most basic step you can take when starting to save money is opening a savings account. Sometimes, though, this can seem like an unnecessary...
 Chris Gottschalk : May 21, 2020, 5:50:00 AM
When you get a savings account, you'll want to see if you have to pay any fees. Here are some savings accounts fees to watch out for.
 Allethea Faye Monfiel : Mar 31, 2026, 5:00:00 AM
A money market account earns higher dividends than a basic savings account, stays fully accessible, and carries zero market risk. Here is how it...