<img src="https://events.xg4ken.com/pixel/v2?tid=KT-N2BAB-3ED&amp;noscript=1" width="1" height="1" style="display:none">
Skip to the main content.

5 min read

How to Build Credit with a Credit Card: Best Practices for Beginners

How to Build Credit with a Credit Card: Best Practices for Beginners

Building credit with a credit card can feel overwhelming at first, especially if you’re starting from scratch or trying to recover from past missteps. If you’ve ever wondered whether one wrong move could set you back or whether small choices really make a difference, you’re not alone. The good news is that building healthy credit habits usually starts with a few steady moves: use your card for small purchases you already have room for in your budget, pay your balance in full and on time each month, and keep your credit utilization low. Those habits may sound simple, but over time they help show lenders you can borrow responsibly and manage credit with consistency.

In this guide, we’ll walk through how credit cards affect your credit score, what to look for in your first card, and a simple 12-month plan to help you build credit with confidence. Whether your goal is to qualify for better rates, make future borrowing more affordable, or simply feel more in control of your financial footing, the right habits can help you get there.

Why Does Building Credit Matter?

Build Credit - a person checking their credit score on the phone

What does it mean to “build credit,” and why is it important?

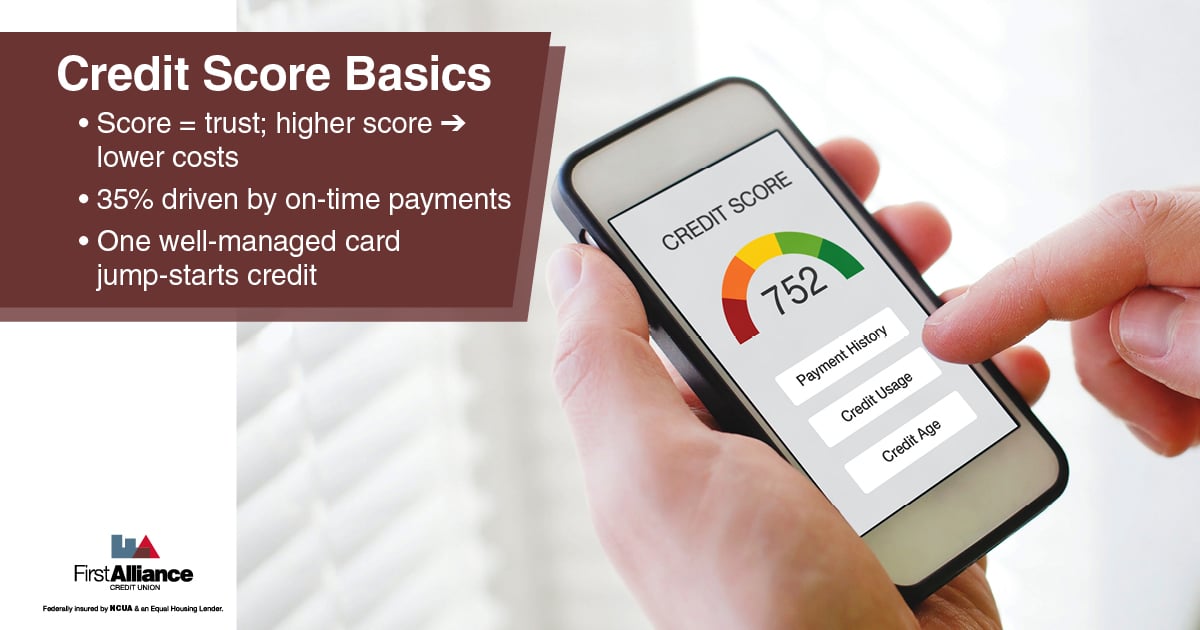
Building credit is just proving you can borrow money and pay it back on time. The higher your score, the lower your future borrowing costs—think smaller deposits for utilities, sweeter car‑loan terms, and fewer rental headaches.

How can a credit card help improve my score?

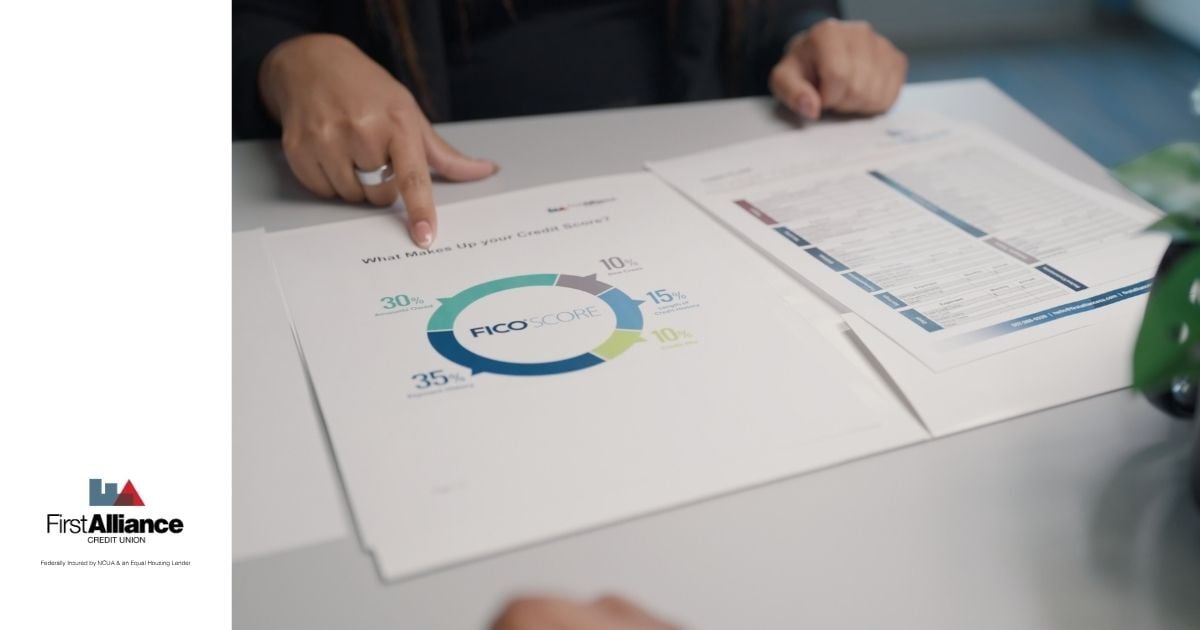
When you pay on time, your card issuer usually reports that payment activity to the three national credit bureaus: Equifax, Experian, and TransUnion. That matters because payment history is the biggest factor in most credit scores, so steady on-time payments can help your score move in the right direction over time. If you want to keep an eye on your progress, you can check your credit reports for free at AnnualCreditReport.com.

Is it okay to carry a balance?

Not if you can avoid it. Carrying a balance means interest starts adding to what you owe, which can make it harder to stay on track. If possible, pay your balance in full each month and use your credit card like a purchase you’ve already planned for in your budget.

What Is Secured Credit Card?

Build Credit - man swiping a card

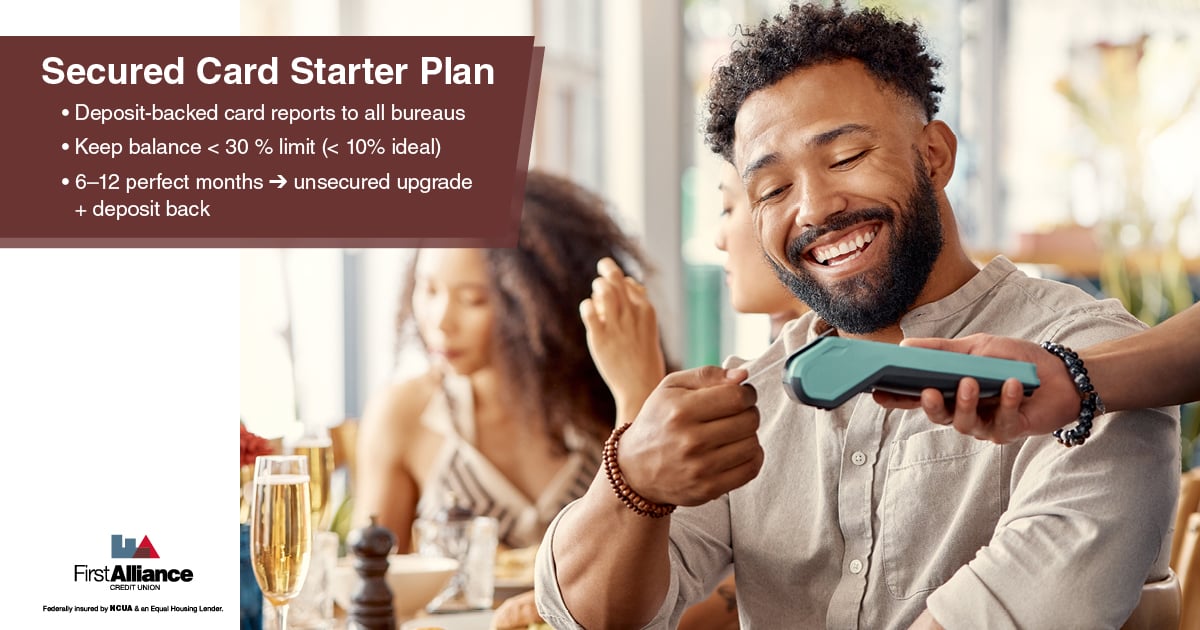
A secured credit card requires a refundable deposit, and that deposit usually becomes your credit limit. For example, if you put down $300, your limit is typically $300. That can make secured cards a practical place to start because approval is often easier, the risk is lower for the issuer, and fees are usually minimal.

Should I start with secured or unsecured?

If you’re brand‑new to credit—or rebuilding—secured is easier to get and reports to all three bureaus. After six to twelve months of on-time payments, many cardholders can move to an unsecured card and get their deposit back.

How many cards should I open while building credit?

One card is usually plenty when you’re building credit. Applying for too many cards in a short stretch can lead to hard inquiries, which may put a temporary dent in your score. It’s usually better to give your first card time to do its job before you think about adding another.

Credit utilization—what is it?

It’s your balance divided by your credit limit. In general, staying below 30% is a good goal, and keeping it under 10% is even better if you can manage it. On a $300 limit, that means trying to keep your balance under $30 for most of the month.

Watch & Learn the Right Payment Method for Every Situation

Press play for Nate’s quick tips on using  credit cards vs. debit cards.

5 Habits That Help Your Build Credit

These five habits can help you build a steady payment history while keeping your credit utilization in a healthy range.

1. Use the card for predictable bills only.

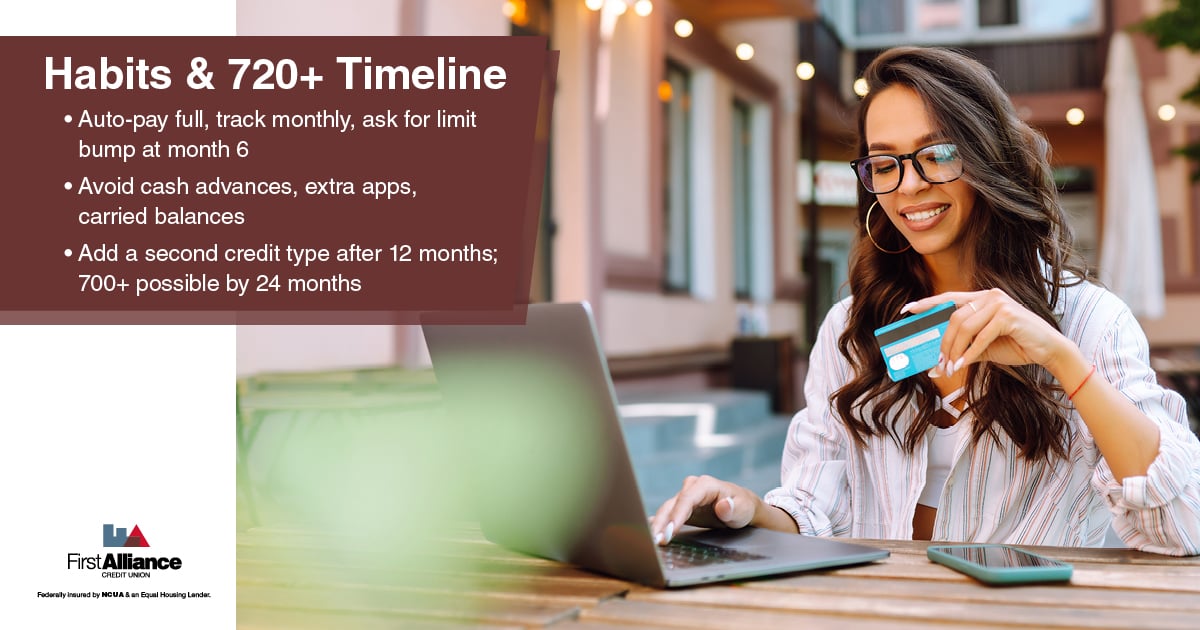
Charge expenses that are already in your budget, like a transit fare or a streaming subscription. Small, recurring purchases give you steady activity to report to the credit bureaus, and you always know you can cover them when the statement arrives. Avoid using the card for anything you couldn't pay for today.

2. Pay in full, early.

Schedule automatic payments a few days before the due date so you never trip over a late-payment fee. Payment history is one of the biggest factors in your credit score, so a single missed payment can undo months of progress. Paying the full statement balance also means you never pay interest.

3. Keep utilization tiny.

Charging small amounts and paying in full keeps the share of your credit limit that you use low. This share is called your credit utilization ratio. For example, on a $300 limit, a $30 balance is 10 percent. Staying below 30 percent is a good goal, and under 10 percent is even better.

4. Monitor progress for free.

Free credit monitoring shows your score updates and helps you spot errors you can dispute. Checking once a month lets you confirm that your on-time payments are being reported and catch anything unfamiliar early. You can learn more about how scores work in our guide to understanding your credit score.

5. Increase limits responsibly.

After about six months of on-time payments, ask your card issuer for a higher limit, and ask whether it requires a hard inquiry first. Even if your spending stays the same, a bigger limit lowers your utilization and can raise your score. Raise your limit to improve your ratio, not to spend more.

Common Credit Card Mistakes to Dodge

  • Paying only the minimum. Interest piles up faster than snow.

  • Maxing out the limit. A $299 balance on a $300 card screams “credit stress” to scoring models.

  • Relying on cash advances. Fees + high APR = debt trap. Build a mini emergency fund instead.

  • Opening multiple cards at once. Each hard inquiry clips points off your score; space new applications six months apart.

  • Skipping the fine print. Penalty APRs or annual fees hide in tiny text—read once, avoid forever.

Your 12‑Month Plan to a 720+ Score

Build Credit - checking her credit on the laptop

Think of it as a steady approach, not a race. The goal is to help you build positive habits, keep your balance manageable, and give your score time to respond to the progress you’re making. Here’s a simple month-by-month plan to follow if you want to build credit step by step without overcomplicating things

Months 1‑3 – Plant the Seed

Put one fixed bill on your secured card and pay it off the moment the statement hits. Those quick, clean payments lay perfect roots in your credit history.

Months 4‑6 – Show Control

Try to keep your spending below 10% of your credit limit. Low balances show scoring models that you’re using credit carefully and not relying too heavily on it.

Months 7‑9 – Widen the Lane

If your card issuer allows it, ask about a credit limit increase or whether you’re ready to move to an unsecured card. A higher limit can lower your utilization ratio if your spending stays the same, and graduating to an unsecured card may also mean getting your deposit back.

Months 10‑12 – Add Variety

If it fits your situation, consider adding one small new line of credit, like a rent-reporting service or a small personal loan. Over time, a more varied credit mix can strengthen your profile and may give your score another boost.

Results vary, but steady on-time payments and low balances give your score the best chance to improve over time. You can also recover from past late payments or a low score, because recent on-time payments matter more than older miistakes

Final Thoughts on Building Credit With a Credit Card

Building credit with a credit card really comes down to a few steady habits: if you’re new to credit, a secured card can be a practical place to start; charge only what you already know you can repay; pay your balance in full and on time each month; and keep your credit utilization low. Over time, those habits can help you build a stronger credit history and feel more confident about where you stand. It also helps to use free credit monitoring so you can track your progress and stay aware of changes to your credit.

Have More Questions About Building Credit? Ask Us Anything! Tap the button for quick, judgment-free answers from your First Alliance team—so you can use your credit card wisely.

Using a Credit Builder Loan for Rebuilding Credit

Using a Credit Builder Loan for Rebuilding Credit

Learn how a Credit Builder Loan from First Alliance Credit Union can help you start rebuilding credit with fixed payments and a savings boost at the...
Read More
Credit Builder Loan vs. Secured Credit Card: What’s the Difference?

Credit Builder Loan vs. Secured Credit Card: What’s the Difference?

Compare a credit builder loan and a secured credit card side by side, and see which First Alliance Credit Union option fits your credit-building...

Read More
Credit Builder Loans: What Are They and How Can They Help You?

Credit Builder Loans: What Are They and How Can They Help You?

Learn how Credit Builder Loans can help you build credit, save money, and achieve your financial goals with guidance from First Alliance Credit Union.

Read More