 Kamel LoveJoy
Advantages and Disadvantages of a Certificate of Deposit for Savings
 Jenna Taubel : Jun 26, 2017, 8:00:00 AM
Learn about the advantages and disadvantages of a certificate of deposit for savings and see if one is right for you.

A Certificate of Deposit is a savings tool that lets you set money aside for a fixed term, like six months or five years, while earning a fixed interest rate. Because you agree to leave those funds in place until the term ends, a Certificate of Deposit will often pay more than a regular savings account. In this guide, we’ll walk through how Certificates of Deposit work, how they compare to savings accounts, how they’re insured, and what to know before opening one..

A certificate of deposit (CD) is a type of savings account offered by banks and credit unions. A CD usually has a fixed term, a fixed interest rate, and a penalty for withdrawing early. Here's what that means:
Higher Interest Rates: Because you’re agreeing to “lock up” your funds for a specific term (like six months or five years), CDs usually offer higher interest rates than regular savings accounts.
Locked-In Funds: Once you put your money in a CD, it stays there for the term you chose. Early withdrawals often come with a penalty, so it’s best for funds you don’t need for day-to-day expenses.
Predictable Returns: Since CDs have fixed rates, you know exactly how much you’ll earn by the end of the term. Jaden doesn’t have to worry about the market affecting his returns; the rate he locks in stays the same.
CDs at a credit union are insured by the National Credit Union Administration (NCUA) up to $250,000 per share owner, per insured credit union, for each account ownership category. CDs at banks are insured up to $250,000 by the FDIC.
The biggest difference comes down to access and flexibility. A savings account lets you add money and withdraw it as needed, while a Certificate of Deposit is designed for money you can leave in place for a set term in exchange for a fixed interest rate. Here’s a simple side-by-side look at how the two compare:
| Features | CD | Savings Account |
| Access to funds | Locked until the term ends, early withdrawal penalty may apply | Available anytime, subject to account rules |
| Interest rate | Fixed for the term | Can change |
| Typical earnings | Usually higher | Usually lower |
| Best for | Money you won't need for a set period | Emergency funds and everyday saving |

A CD works by trading access to your money for a guaranteed rate. To see how that plays out, consider Jaden. He just started his first full-time job and has saved $1,500. He wants his money to grow, but he doesn't want to lose access to it for years. He decides to put the $1,500 into a one-year CD. Here's how the process of opening a CD works:
Choose a Term: Jaden picks a term that fits his comfort level with locking up his funds. A one-year CD might feel “safe” since it’s not too long.
Deposit the Funds: He puts his $1,500 into the CD, and the bank locks in a fixed interest rate for that year.
Earn Interest: Over that year, Jaden’s money quietly grows at the guaranteed rate.
Withdraw or Renew: When the term is up, Jaden can either take his original $1,500 plus the interest he earned or roll it over into a new CD if he wants to keep growing it.
Pro Tip: Before opening a CD, make sure you have an emergency fund that is easy to access. CDs can be useful for savings you don't need right away, but they may not be ideal for money you could need on short notice.
Fixed, Higher Interest Rates: CDs offer stable, predictable growth. Jaden doesn’t have to stress about his rate changing during the year.
Security: His deposit is insured, so his savings are safe.
Saving Discipline: With his money locked in, Jaden won’t be tempted to dip into his savings for impulse buys.

Now, Jaden doesn’t want to feel like his money is completely locked away. That’s where CD laddering comes in! A CD ladder is a strategy where you invest in multiple CDs with different maturity dates, so you get the benefit of higher rates without losing access to all your savings.
How to Set Up a CD Ladder: Let’s say Jaden wants to try this with his $1,500. Here’s how he could set up a simple three-rung CD ladder:
Divide the Funds: He splits his $1,500 into three equal parts.
Invest in Three CDs: Jaden puts $500 in a one-year CD, another $500 in a two-year CD, and the last $500 in a three-year CD.
Reinvest Upon Maturity: When the one-year CD matures, he can either use the funds or roll them into a new three-year CD, keeping the ladder going.
By doing this, Jaden can access part of his savings every year if he needs it, while the rest keeps growing at higher rates. It’s the perfect strategy if you want a balance between growth and flexibility.


For savers with a larger nest egg, Jumbo CDs offer another option. A Jumbo CD is just like a regular CD but with one major difference: it requires a big initial deposit—typically $100,000 or more—and in return, you get an even better interest rate.
Minimum Deposit: Jumbo CDs require a large initial deposit, while regular CDs are more accessible.
Higher Interest Rates: Because of the big deposit, Jumbo CDs usually pay slightly better.
Although Jumbo CDs are great if you’ve got a lot of cash on hand, they’re really for those who can comfortably set aside a significant amount without needing access to it. For now, Jaden will stick with regular CDs, but it’s good to know about this option for the future.
CDs are a great way to grow your money safely if you’re not in a hurry to access it. For first-time savers like Jaden, a CD ladder can provide flexibility by allowing access to some savings each year while still earning higher returns. Jumbo CDs are a solid choice when you have a bigger amount to invest and want the best possible rate. In the end, CDs can be a simple, worry-free savings tool that helps you meet your goals with a little patience and a bit of strategy. If you’d like to see what a CD can do for you, become a member of First Alliance Credit Union today.

 Jenna Taubel : Jun 26, 2017, 8:00:00 AM
Learn about the advantages and disadvantages of a certificate of deposit for savings and see if one is right for you.
 Chris Gottschalk : Jun 6, 2023, 4:30:00 AM
Why are CDs Safe Investments? There are three key reasons why. Here are 3 ways CDs keep your money safe against everything from recessions to...
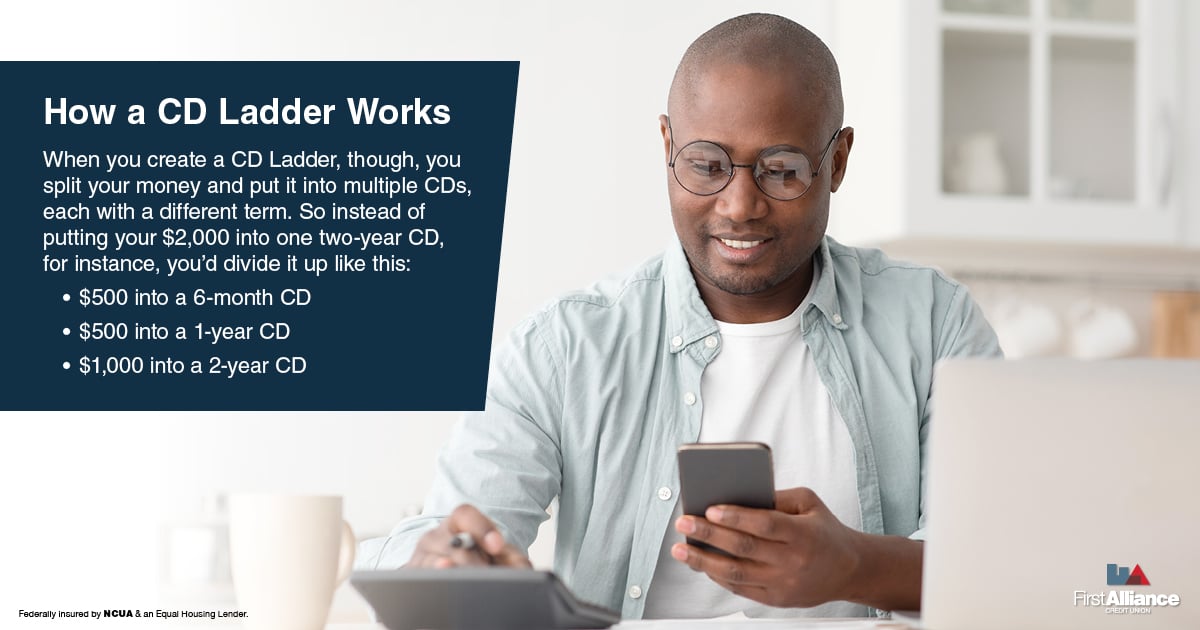 Chris Gottschalk : Feb 2, 2023, 4:45:00 AM
Knowing how to build a CD ladders lets you maximize your savings and avoid the risk of investing. Here's what you need to know about building CD...